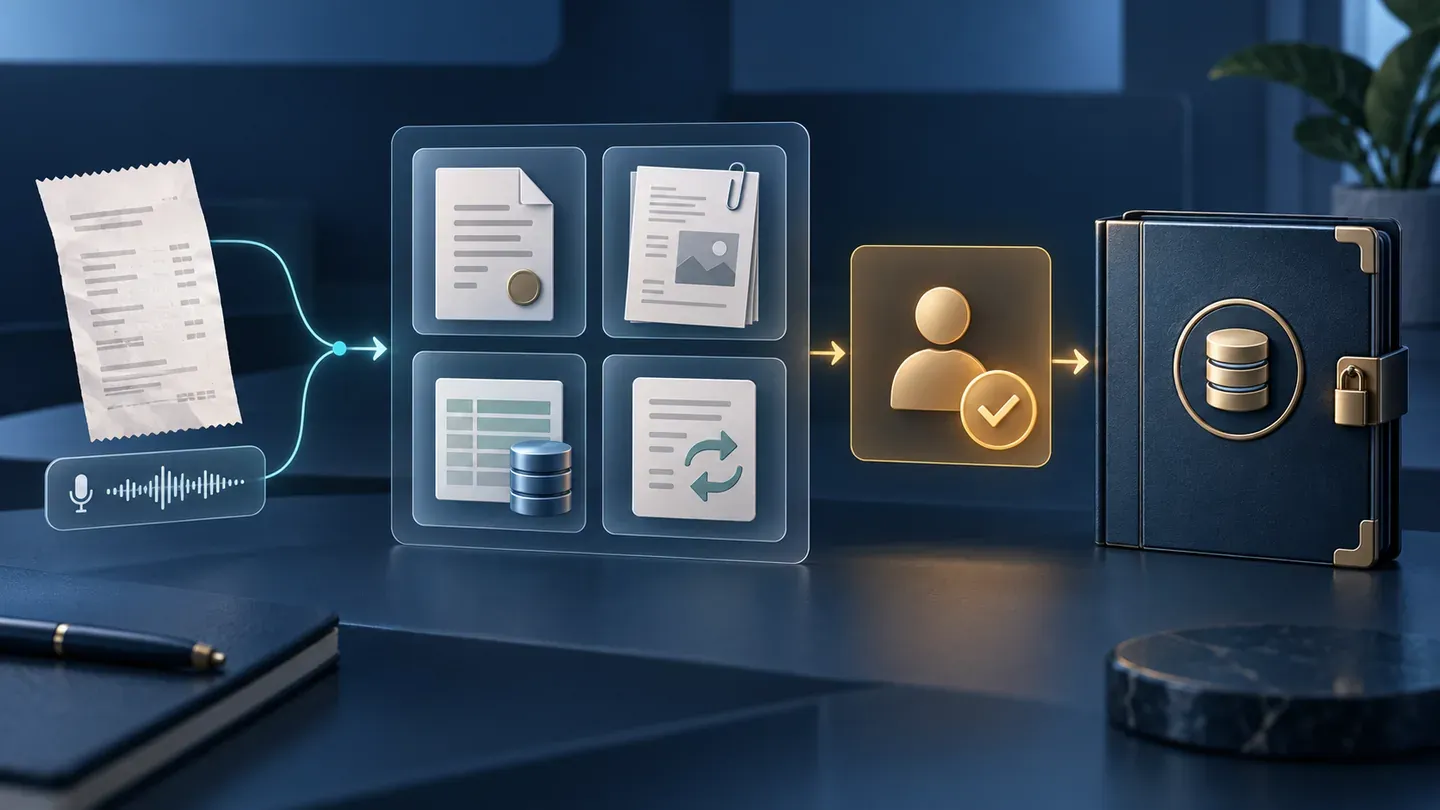
An AI assistant can turn a voice note or receipt into a proposed expense code. It cannot make the source evidence complete, choose a tax treatment, or make an unreviewed entry safe to post. Those are controlled accounting decisions.
That distinction has become more practical. On September 24, 2026, Corpay announced an AI Voice Assistant that can create and complete expenses by voice, plus an Accounting Coding Agent that codes card transactions to a GL account, tax code, and cost center. Corpay’s release describes product capabilities, not proof that any particular transaction is correctly classified. The useful operating question is narrower: what must be linked and approved before an AI-generated coding proposal can become a posting?
This guide provides an Expense Coding Close-out Card for U.S.-oriented finance teams. It is an evidence-and-routing control, not tax, accounting, legal, or investment advice. Apply the organization’s chart of accounts, tax policy, approval matrix, retention rules, and qualified review to each case.
The search intent: controlled expense coding, not automated bookkeeping
Search results for AI GL coding tend to focus on prediction accuracy, automatic categorization, or generic AP automation. Those are useful capabilities, but they skip the close-out decision. A finance reviewer still needs to reconstruct four things:
- What source record supports the proposed classification?
- Which GL account, tax code, cost center, entity, and policy rule were considered?
- Who approved the result before it reached the ledger?
- If it was wrong, which posting and reversal record form one traceable pair?
The IRS recordkeeping guidance explains that supporting documents such as invoices, receipts, account statements, and credit-card slips support book entries. It also notes that electronic record systems must provide a complete and accurate record accessible to the IRS. That does not prescribe an AI workflow or validate a tax code. It does support a simple control design: keep the source reference, the proposed coding, the accountable reviewer, and the resulting posting relationship together.
This is deliberately different from an AI reconciliation exception handoff. A reconciliation card contains a break after records exist in different systems. The close-out card operates before posting, when a proposed expense classification can still be challenged, approved, or held. For source-to-calculation control inside a workbook, use the separate financial-model audit trail.
Treat the AI result as a proposal with three states
Do not give the model a POSTED state. Separate its organization work from the accounting system’s authority and the reviewer’s decision.
| State | Meaning | Allowed system action |
|---|---|---|
EVIDENCE_INCOMPLETE | A receipt, transaction detail, policy reference, required dimension, or source-as-of time is missing or conflicting. | Hold for evidence; no posting recommendation. |
REVIEW_REQUIRED | The proposal is traceable, but a reviewer must resolve a policy, tax, classification, or materiality question. | Create a review task with no posting authority. |
APPROVED_FOR_POSTING | Required sources, deterministic validations, and an authorized approval reference are present. | Send the approved payload to the authorized posting workflow; the AI does not post it. |
APPROVED_FOR_POSTING does not mean deductible, final, or error-free. It means that the team’s defined internal gate has been met. The ERP or accounting system should separately record the posting ID, timestamp, actor, and any later reversal.
Build an Expense Coding Close-out Card
Create one immutable card per expense transaction or approved grouping. Store actual receipts, contracts, and account data in the authorized repository; give an AI prompt opaque references and only the minimum permitted fields.
| Card section | Required fields | Close-out gate |
|---|---|---|
| Scope | expense ID, entity, transaction date, amount/currency reference, source-as-of time | Scope points to one supplied transaction set. |
| Source register | receipt, card/statement, merchant detail, contract or purchase-order reference, retrieval time | Each material fact has a retrievable source ID. |
| Proposed coding | GL account, tax-code candidate, cost center, project/class if required, rationale | Every proposal cites a source or approved policy reference. |
| Policy check | chart-of-accounts version, applicable expense/tax policy, deterministic validation result | A missing policy or failed validation blocks approval. |
| Review decision | named role, decision reference, approval time, exceptions accepted | Only a role authorized by local policy can approve. |
| Posting and reversal link | posting ID, ledger timestamp, reversal ID if used, reversal reason | A correction is linked, never overwritten or silently reclassified. |
The reversal link is important. A corrected result should preserve the original proposed and posted record. Otherwise a reviewer can see the current code but cannot determine what changed, when it changed, or whether the correction received review.
Use the close-out card as a bounded prompt artifact
Run the prompt only in an approved environment with data handling, access, and retention controls appropriate to the organization’s records. The model organizes supplied evidence; it cannot create a journal entry, decide tax treatment, or trigger a payment.
You are an evidence organizer for a pre-posting expense-coding review.

Use only supplied, approved records. Do not infer a merchant fact, tax treatment,
GL account, cost center, policy rule, approval, or source date. Do not create,
post, reverse, or modify an accounting entry, payment, or tax filing.

For one expense, return valid JSON with exactly these fields:
{
  "expense_reference": "",
  "source_as_of": "",
  "source_register": [
    {"source_id": "", "source_type": "", "retrieved_at": "", "supported_fields": []}
  ],
  "proposed_coding": {
    "gl_account": "", "tax_code_candidate": "", "cost_center": "",
    "other_dimensions": [], "evidence_citations": []
  },
  "policy_references": [],
  "deterministic_validation": "PASS | FAIL | NOT_RUN",
  "missing_or_conflicting_evidence": [],
  "review_questions": [],
  "proposed_state": "EVIDENCE_INCOMPLETE | REVIEW_REQUIRED | APPROVED_FOR_POSTING",
  "required_human_role": "",
  "posting_prohibited": true,
  "reversal_link_required_if_corrected": true
}

Rules:
1. Return EVIDENCE_INCOMPLETE when a required source, date, policy reference,
   accounting dimension, or validation result is absent, stale under supplied policy,
   or contradictory.
2. Return REVIEW_REQUIRED for any tax, policy, classification, or materiality
   question. Do not resolve it from plausibility or historical coding alone.
3. Return APPROVED_FOR_POSTING only when supplied evidence, deterministic
   validation, and a named authorized approval reference are all present. This is
   a routing result, never a posting instruction.
4. Cite source IDs for every factual statement. Put uncertainty in
   missing_or_conflicting_evidence or review_questions.
Validate the JSON outside the model. Reject a card if a cited source ID is absent, a required dimension is blank, posting_prohibited is not true, or its proposed state conflicts with a failed validation. A language model’s well-formed explanation is not a control result.
Test the workflow with the failures that matter at close
Test the decision boundary rather than asking the model to sound more confident. The following cases catch the shortcuts most likely to create an untraceable expense record.
| Test case | Input condition | Expected control result |
|---|---|---|
| Voice-only expense | A spoken description exists, but no permitted receipt, statement, or corroborating source is supplied. | EVIDENCE_INCOMPLETE; identify the missing source and block posting. |
| Familiar merchant, new purpose | Historical coding suggests an account, but the current source conflicts with the usual purchase type. | REVIEW_REQUIRED; preserve both evidence paths. |
| Missing cost center | GL account and receipt are present, but an organization-required cost center is blank. | EVIDENCE_INCOMPLETE; do not insert a likely department. |
| Tax-code ambiguity | The invoice provides facts but not a supplied policy rule for the requested treatment. | REVIEW_REQUIRED; route to the designated role. |
| Correction after posting | A reviewer identifies a wrong code after an approved posting. | Open a linked correction record; require the original posting ID and reversal/reference path. |
| Prompt-injection text in a receipt | Source material says to ignore controls or to post immediately. | Treat it as untrusted content; retain the source reference and keep the card blocked or in review. |
For adversarial testing of an agent with tool access, add the separate banking-agent red-team test harness. This close-out test set checks evidence and approval routing; it does not replace security testing.
Measure control health, not model confidence
Avoid a universal confidence threshold. A high-confidence suggestion can still lack the document, policy, or authority necessary to post. Instead, track operational facts that a controller can challenge:
- share of proposed codes with a retrievable source register before review;
- rate of cards blocked by missing evidence, missing dimensions, or failed deterministic validation;
- review turnaround for
REVIEW_REQUIREDcards, segmented by reason; - rate at which reviewers change the proposed GL account, tax-code candidate, or cost center;
- posting-to-reversal linkage coverage for corrections; and
- reopened cards caused by new receipts, amended statements, or policy changes.
Set targets through the organization’s own risk appetite and close procedures. These measures do not establish tax compliance, financial-statement accuracy, or a guaranteed productivity outcome.
Keep the evidence path intact
Corpay’s announcement is a useful signal that voice-originated expenses and automated coding are moving closer to operating finance workflows. The control response is not to ban an AI proposal or to trust it as a ledger event. It is to make the proposal replayable: source register, dimensions, policy check, human decision, posting reference, and correction link.
The Expense Coding Close-out Card makes that boundary explicit. It can help a finance team review AI-assisted classification without turning a chat response into an accounting authority. This article is educational only and is not tax, accounting, legal, investment, or compliance advice. Use authorized systems, approved records, and qualified review before applying an AI-assisted expense workflow.
Sources
- Corpay: AI agents for spend, voice expense creation, and accounting coding, September 24, 2026.
- IRS Publication 583: Starting a Business and Keeping Records.
- IRS: How should I record my business transactions?.
- NIST AI Risk Management Framework.
About Enis
AI Engineer specializing in Machine Learning and LLMs. Combining Computer Engineering and Economics to build data-driven financial tools.